
September 24, 2026
Fund vs SMA vs Direct Mandate: What Institutional Allocators Should Know
Institutional investors can access a quantitative strategy through different investment structures. Three common routes are investing in a fund, using a separately managed account (SMA), or establishing a direct mandate with the manager. Each can provide exposure to the same underlying investment process, but the way assets are held, managed, monitored, and customized can be very different.
The choice therefore goes beyond strategy performance. Allocators also need to consider control, transparency, operational complexity, liquidity, customization, and the size of the allocation.
Investing through a fund
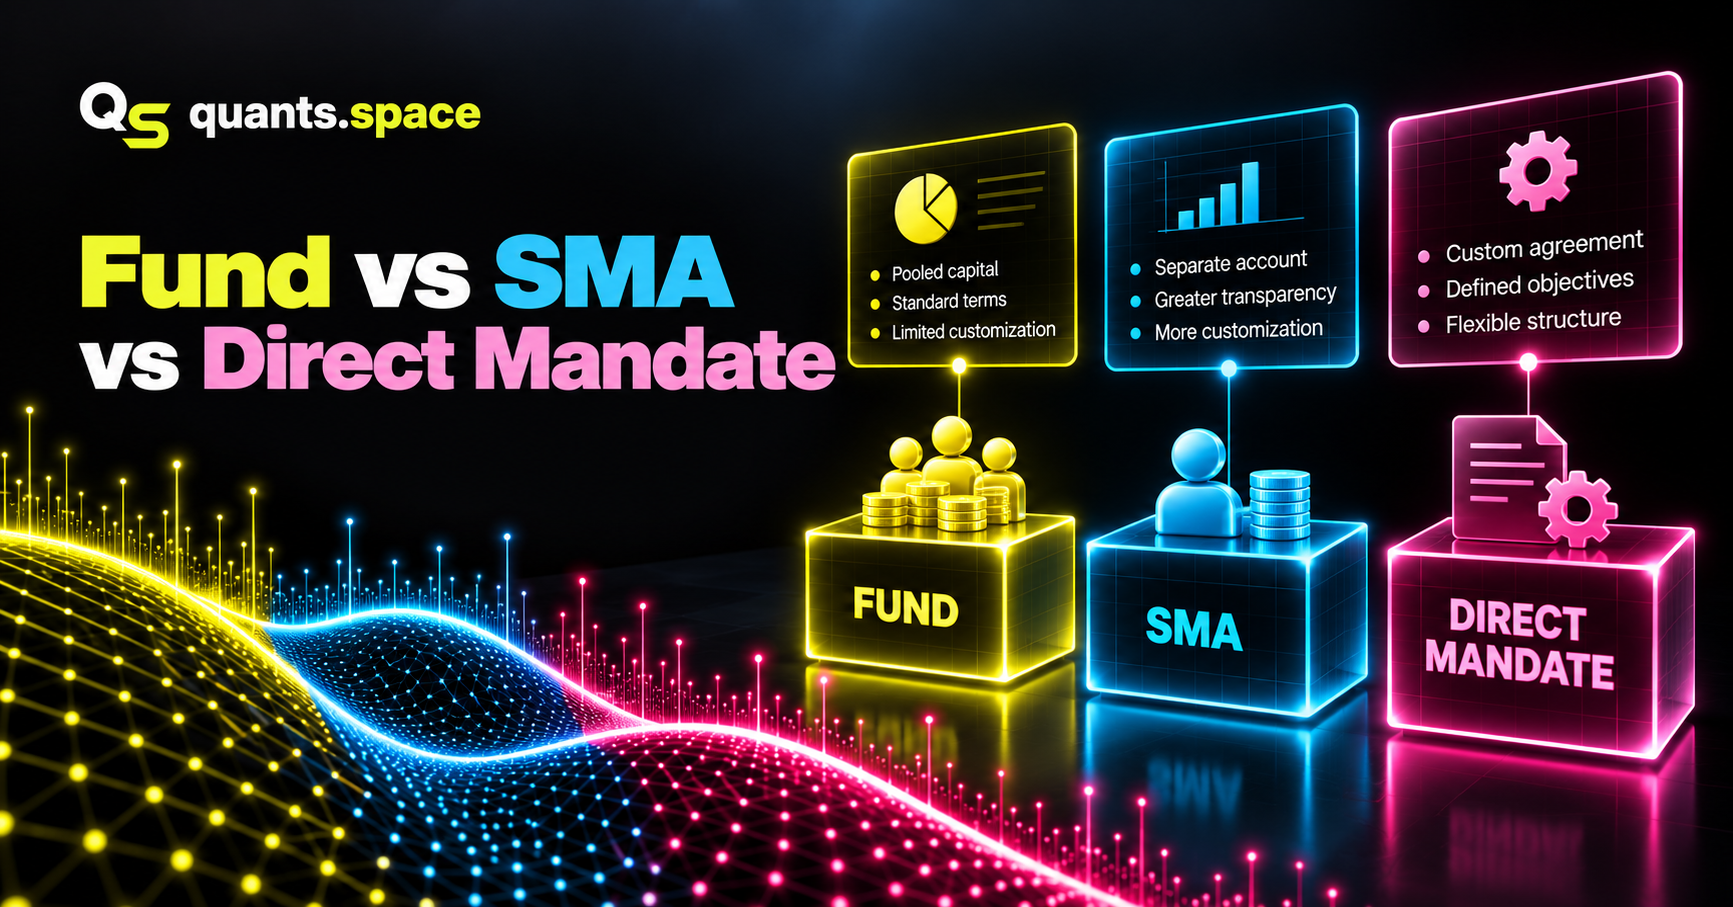
A fund pools capital from multiple investors into a single investment vehicle. The manager operates the portfolio according to the fund's investment mandate, while investors own interests in the fund rather than the individual assets held by it.
This structure can make access relatively straightforward because much of the operational framework already exists. The manager has established the vehicle, service providers, reporting processes, subscription terms, and redemption rules. An allocator can evaluate the strategy and fund structure and then subscribe under the existing terms.
The trade-off is that individual investors usually have limited control over how the portfolio is managed. They follow the fund's investment guidelines and liquidity terms, while customization may be limited. Transparency also depends on what the manager provides through reports and investor communications.
How an SMA changes the relationship
In a separately managed account, the allocator's assets are managed separately rather than pooled with capital from other investors. The account is typically established for one investor, while the manager receives authority to trade according to an agreed mandate.
For institutional allocators, this can provide greater transparency and control. Depending on the arrangement, the investor may be able to see positions, transactions, exposures, and performance directly through the account infrastructure. Assets also remain segregated from those of other investors.
An SMA can offer more flexibility than a pooled fund. Investment guidelines, risk limits, permitted instruments, or other parameters may be adapted to the allocator's requirements. However, that flexibility also creates additional operational work. Account setup, custody, permissions, reporting, and monitoring all need to be established between the parties.
What is a direct mandate?
A direct mandate is a broader arrangement in which an allocator appoints an investment manager to manage capital according to agreed objectives and restrictions. Depending on the setup, an SMA can itself be the structure used to implement a direct mandate.
The distinction is therefore not always as clean as “fund vs SMA vs direct mandate” suggests. A fund is an investment vehicle, an SMA describes a separately managed account structure, while a direct mandate describes the investment relationship and instructions agreed between the allocator and manager.
For example, an institution might appoint a quant manager under a direct mandate and implement that mandate through a segregated account. The specific structure depends on the investor, manager, jurisdiction, custody arrangements, and investment requirements.
Control and customization
One of the clearest differences between these approaches is how much influence an individual allocator has over the implementation of the strategy.
In a pooled fund, investors generally accept a common investment mandate. With a separately managed arrangement, there may be more scope to define exposure limits, permitted instruments, leverage constraints, liquidity requirements, or other portfolio rules. A direct institutional mandate can go further by specifying investment objectives and restrictions negotiated specifically between the investor and manager.
More customization is not automatically better. Every additional restriction can affect how the strategy is implemented, and a heavily customized version may behave differently from the manager's flagship strategy. Allocators therefore need to understand whether their requirements change the expected risk, return, or capacity characteristics.
Transparency and monitoring
Quant allocators often want to understand what is happening after capital has been allocated, particularly when evaluating exposure, drawdowns, liquidity, and risk.
A fund provides reporting according to its established reporting framework. An SMA or segregated mandate can potentially provide more direct visibility because the investor has a dedicated account. Depending on the infrastructure, performance and exposure may be monitored using account-level data rather than relying exclusively on periodic manager reports.
The amount of transparency still depends on the agreement and technical setup. Having a separate account does not automatically mean an investor receives every detail of the manager's models, signals, or intellectual property.
Operational complexity matters
The structure with the greatest flexibility may also require more work to establish and maintain. A fund already has much of its legal and operational infrastructure in place, while an SMA or bespoke mandate can require coordination between the manager, allocator, custodian, broker, administrators, and other service providers. This can also affect minimum allocation size. A manager may be willing to offer customized terms only when the allocation is large enough to justify the additional operational burden. Smaller investors may therefore find a pooled fund more practical even when they would prefer greater customization.
Fund, SMA, or direct mandate?
There is no single structure that works for every institutional allocator. The decision depends on what the investor needs from the relationship.
A pooled fund can provide relatively standardized access to a strategy. An SMA can offer segregated assets, greater visibility, and potentially more control over implementation. A direct mandate allows the allocator and manager to define a more specific investment relationship, which may itself be implemented through a separately managed account.
The underlying quant strategy may be similar across these arrangements, but the investor experience can be very different. Before allocating, institutions need to evaluate both sides of the decision: the strategy they want to access and the structure through which they will access it.