October 29, 2026
What Institutional Investors Expect From Quant Manager Reporting
Institutional investors need reliable information to evaluate their investments in quantitative strategies. A monthly return figure provides a starting point, but it offers limited insight into how those returns were generated, which risks the portfolio carries, or whether the strategy continues to operate as expected.
For quant managers, investor reporting is an important part of maintaining institutional relationships. Consistent, transparent reports help allocators monitor performance, meet internal oversight requirements, and identify changes that may affect their investment decisions.
Understanding what institutional investors expect can help managers build reporting processes that support both initial due diligence and ongoing portfolio monitoring.
Consistent and Verifiable Performance Data
Performance reporting is usually the foundation of an institutional investor report. Allocators expect accurate returns calculated using a consistent methodology, with clear explanations of whether figures are presented gross or net of fees.
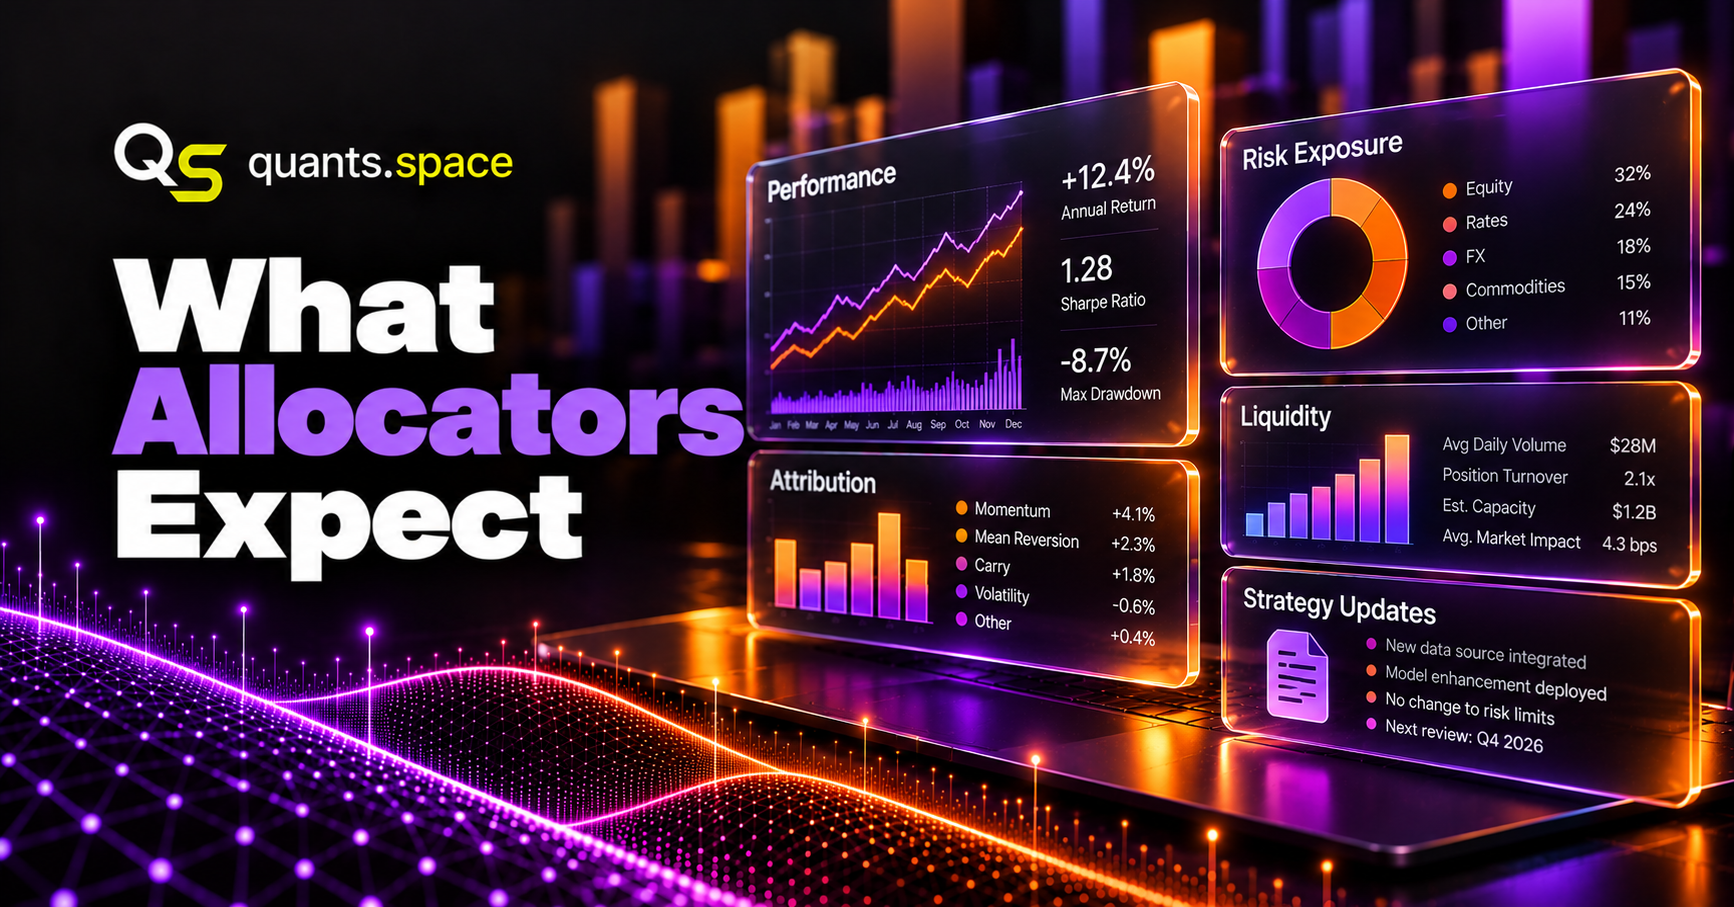
Monthly returns, cumulative performance, and relevant benchmarks help investors evaluate results over time. Common metrics include annualized return, volatility, Sharpe ratio, maximum drawdown, and recovery periods. Managers should also explain material changes in calculation methods or reporting assumptions.
Where appropriate, independently verified performance records can provide additional confidence. Investors may request supporting documentation to reconcile reported results with administrator records or other independent sources.
Performance Attribution and Return Drivers
Institutional investors want to understand which factors contributed to a strategy's performance. For systematic managers, attribution can help explain whether returns came from expected sources or from exposures outside the original investment thesis.
Depending on the strategy, reporting may break down performance by asset class, market, trading signal, geographic region, or strategy component. A multi-strategy manager might show how individual models contributed to overall results, while a market-neutral equity strategy could report factor-level performance.
Attribution should be sufficiently detailed to support investor analysis without revealing proprietary trading signals. Clear explanations of unusual gains or losses are particularly useful when market conditions change.
Risk Exposures and Portfolio Characteristics
Return figures become more meaningful when investors can assess the risks taken to generate them. Institutional allocators commonly monitor leverage, concentration, volatility, liquidity, and exposure to relevant markets or factors.
For quantitative strategies, correlations and factor sensitivities may be especially important. A strategy designed to diversify an institutional portfolio can become less attractive if its exposures increasingly overlap with existing investments.
Managers should present risk metrics consistently and explain significant changes. Where appropriate, reporting can include stress tests, scenario analysis, and comparisons with established risk limits.
Drawdowns and Unexpected Performance
Drawdowns often lead to additional questions from institutional investors. Allocators need to understand whether losses remain consistent with the strategy's expected behavior and whether risk controls are operating as intended.
A useful report explains the magnitude and duration of a drawdown, its main contributing factors, and any material changes in portfolio exposures. It should also identify whether the manager has intervened and explain the rationale behind those decisions.
Managers should avoid presenting recovery forecasts as reliable expectations. Clear explanations supported by available data are more useful than assurances that losses will reverse.
Strategy Changes and Model Updates
Quantitative strategies evolve as managers refine models, incorporate new datasets, or adapt their infrastructure. Institutional investors generally expect to be informed about material changes that could affect the strategy's risk profile or investment process.
These changes might include entering new markets, modifying portfolio construction rules, adjusting leverage limits, or introducing additional trading models. Routine technical improvements may require less detailed communication, depending on their significance.
Managers should distinguish between normal research development and changes that alter the original investment thesis. Documenting the reasons for material updates helps investors assess whether the strategy remains consistent with their allocation objectives.
Liquidity, Capacity, and Operational Information
Institutional reporting also needs to address factors that influence the manager's ability to operate and manage external capital. Liquidity conditions, strategy capacity, and operational developments can affect an investment even when recent performance appears stable.
Allocators may want updates on assets under management, changes in trading volumes, execution costs, and capacity utilization. For strategies operating in less liquid markets, information about market depth and potential liquidation constraints may be particularly relevant.
Material operational developments should also be communicated. These may include changes in service providers, significant technology incidents, key personnel departures, or issues affecting business continuity.
Reporting Frequency and Communication Standards
Monthly performance reports are common, but institutional investors may require additional information depending on their mandates and risk monitoring procedures. Some allocators request more frequent exposure data, while others rely on monthly reports supplemented by quarterly reviews.
The reporting schedule should be agreed upon early in the relationship. Managers should also establish procedures for communicating significant events, such as unexpected drawdowns, risk limit breaches, or operational disruptions.
Consistency matters as much as frequency. Delivering reports on time, maintaining stable definitions, and explaining revisions help investors integrate manager data into their own monitoring systems.
Making Reports Useful for Investment Committees
Institutional investment teams often need to present manager performance to risk committees, investment committees, and other stakeholders. Reports should therefore make important information easy to locate and interpret.
A clear executive summary can highlight recent performance, major risk developments, and significant changes to the strategy. Supporting tables and charts can then provide the detail required for further analysis.
Managers should use consistent terminology and avoid unnecessary technical complexity. Investors may have quantitative expertise, but reporting should remain accessible to stakeholders who are less familiar with the strategy's implementation.
Building a Reliable Reporting Process
As a quant firm grows, preparing institutional reports manually can become increasingly difficult. Data may need to be collected from trading systems, risk platforms, administrators, and operational records.
Automating data collection and standard calculations can improve consistency and reduce reporting errors. However, automated outputs still require validation, particularly when market data, accounting records, or portfolio structures change.
Managers should establish clear responsibilities for reviewing and approving reports before distribution. Version control, documented methodologies, and reconciliation procedures help maintain accuracy over time.
Reporting as Part of Institutional Readiness
Institutional investors expect reporting that allows them to understand performance, monitor risks, and evaluate whether a manager continues to meet their investment requirements.
For quant managers, effective reporting depends on accurate data, consistent methodologies, clear explanations, and timely communication. These practices support transparency during both favorable and difficult market conditions.
A well-structured reporting process also demonstrates operational maturity. It gives allocators the information they need to make informed decisions and helps managers maintain productive, long-term institutional relationships.