
October 15, 2026
What Should Be in an Institutional Quant Tear Sheet?
Institutional allocators reviewing quantitative trading strategies need to understand their performance, risk profile, and investment approach quickly. Before requesting a detailed presentation or starting formal due diligence, investors often examine a strategy tear sheet to determine whether an opportunity fits their portfolio.
A well-prepared quant tear sheet summarizes essential performance data, strategy characteristics, and investment terms in a clear, consistent format. For emerging quant managers, it can help establish credibility and make initial conversations with institutional investors more productive.
What is a quant strategy tear sheet?
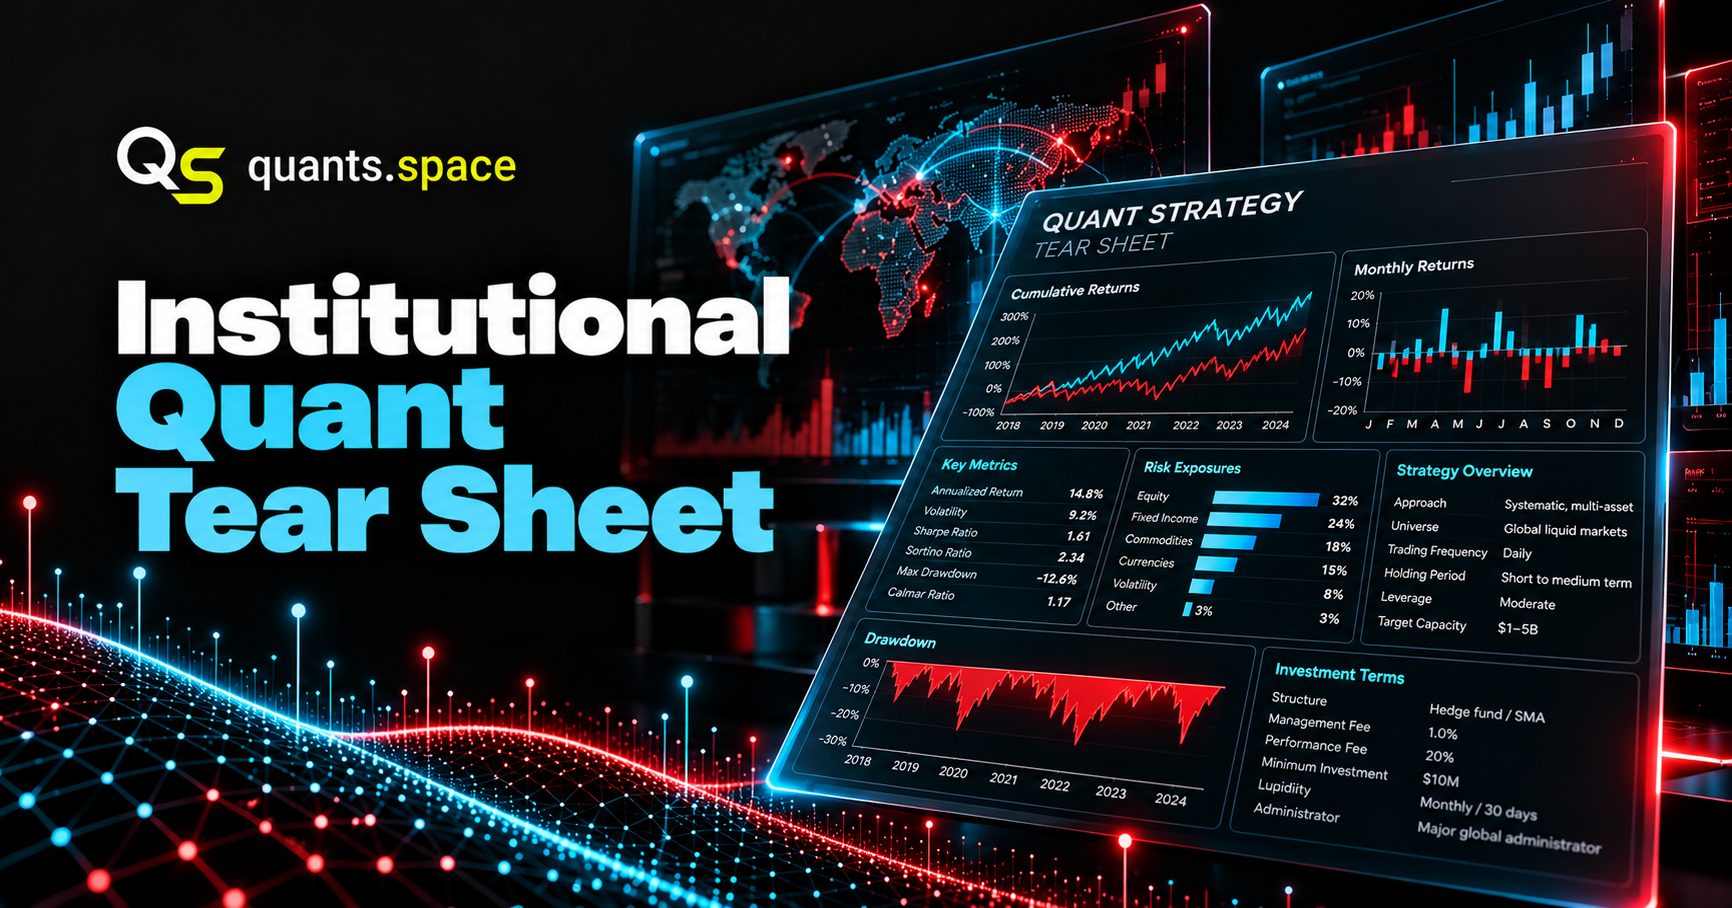
A quant strategy tear sheet is a concise document presenting the key characteristics and historical results of a quantitative investment strategy. It typically includes performance metrics, risk statistics, strategy information, and operational details relevant to prospective investors.
Unlike a full investment presentation, a tear sheet is designed for quick evaluation and comparison. It is usually one or two pages long, allowing allocators to screen multiple managers efficiently. The information should be current, clearly labeled, and supported by reliable data.
Performance metrics and historical returns
Performance is often the first section investors examine, but cumulative returns alone provide limited insight into strategy quality. Institutional allocators need metrics that describe both returns and the risks taken to achieve them.
A useful quant tear sheet typically includes:
- Annualized return and volatility
- Sharpe and Sortino ratios
- Maximum drawdown and Calmar ratio
- Monthly and year-to-date returns
- Strategy inception date and reporting period
These metrics help investors compare strategies with different risk profiles. For example, two managers may deliver similar annualized returns but exhibit significantly different volatility, drawdowns, or downside risk.
Managers should clearly indicate whether returns are gross or net of fees, specify the reporting currency, and distinguish live trading performance from backtested results. Any material changes in strategy methodology should also be disclosed.
Performance charts and monthly returns
Visual information helps allocators understand how a strategy has performed over time. An equity curve shows cumulative returns and highlights periods of growth, stagnation, and decline, while a monthly performance table makes it easier to assess consistency across different market conditions.
A drawdown chart can provide additional insight into the depth and duration of historical losses. All charts should use clearly labeled axes, consistent reporting periods, and transparent calculation methods. Selectively presenting favorable periods can undermine confidence in the results.
Strategy description and investment approach
Institutional investors need to understand what generates a strategy's returns. A tear sheet should briefly explain the investment approach, trading universe, and primary sources of expected performance without revealing proprietary signals.
For example, a manager might describe a systematic trend-following strategy trading liquid futures across equities, fixed income, currencies, and commodities. Additional information may include trading frequency, typical holding periods, directional exposure, and leverage usage.
These details help allocators assess how a strategy might fit alongside existing portfolio investments and whether it introduces new sources of risk or return.
Risk exposures and portfolio characteristics
Historical performance metrics describe past results, but investors also need information about current risks. Depending on the strategy, relevant disclosures may include gross and net exposure, leverage, asset class allocation, liquidity, concentration, and estimated strategy capacity.
The most useful metrics depend on the investment approach. A high-frequency market-making strategy has different risk characteristics from a medium-term trend-following portfolio, so managers should prioritize disclosures that reflect their actual trading activity.
Clear risk reporting helps allocators evaluate potential drawdowns, liquidity requirements, and exposure to broader market movements.
Performance verification and transparency
Institutional allocators need confidence that reported results reflect actual trading activity. A tear sheet should identify the source of performance data and explain whether the track record has been independently verified.
Broker statements, administrator records, and read-only API connections can provide supporting evidence for live trading results. Managers should also disclose limitations such as short track records, simulated performance, or periods when a strategy was inactive.
Separating verified live performance from unaudited results and backtests helps investors assess the reliability of the information presented.
Operational details and investment terms
A tear sheet should include enough operational information for allocators to determine whether an investment is feasible. Relevant details may include assets under management, management and performance fees, minimum investment, liquidity terms, and available investment structures.
Managers may also specify whether the strategy is offered through a hedge fund, separately managed account (SMA), or another arrangement. Information about custody, administration, and regulatory status may be relevant depending on the structure and target investors.
Clear investment terms allow allocators to identify potential operational or structural limitations before beginning more extensive due diligence.
Common mistakes to avoid
One common mistake is emphasizing attractive returns while providing insufficient information about drawdowns, leverage, or risk exposures. Institutional investors need a balanced assessment of performance rather than a document focused exclusively on favorable results.
Inconsistent reporting can also create problems. Unclear fee treatment, different calculation periods, and missing methodology notes make comparisons difficult. Excessive technical detail may further reduce readability, especially when essential information becomes difficult to locate.
A tear sheet should present the most relevant facts clearly, with detailed supporting documentation available during due diligence.
Preparing a tear sheet for institutional review
An effective institutional quant tear sheet combines performance metrics, strategy information, risk disclosures, and verifiable supporting data. It should help allocators understand the investment opportunity and identify questions requiring further investigation.
For quant managers seeking institutional capital, regularly updated information, consistent reporting, and transparent calculations can make the initial screening process more efficient. A tear sheet cannot replace institutional due diligence, but it provides an important starting point for evaluating a quantitative trading strategy.