October 30, 2026
When Should Allocators Redeem From a Quant Strategy?
Allocating capital to a quantitative trading strategy requires extensive due diligence, but deciding when to exit can be equally challenging. A manager may experience a prolonged drawdown, changes in market conditions, or unexpected shifts in portfolio exposures. For institutional investors, the question is whether these developments justify withdrawing capital or simply require closer monitoring.
Redeeming too early can mean abandoning a strategy before it recovers, while waiting too long may expose the portfolio to risks that no longer fit the original investment mandate. A structured review process helps allocators make decisions based on evidence rather than short-term performance.
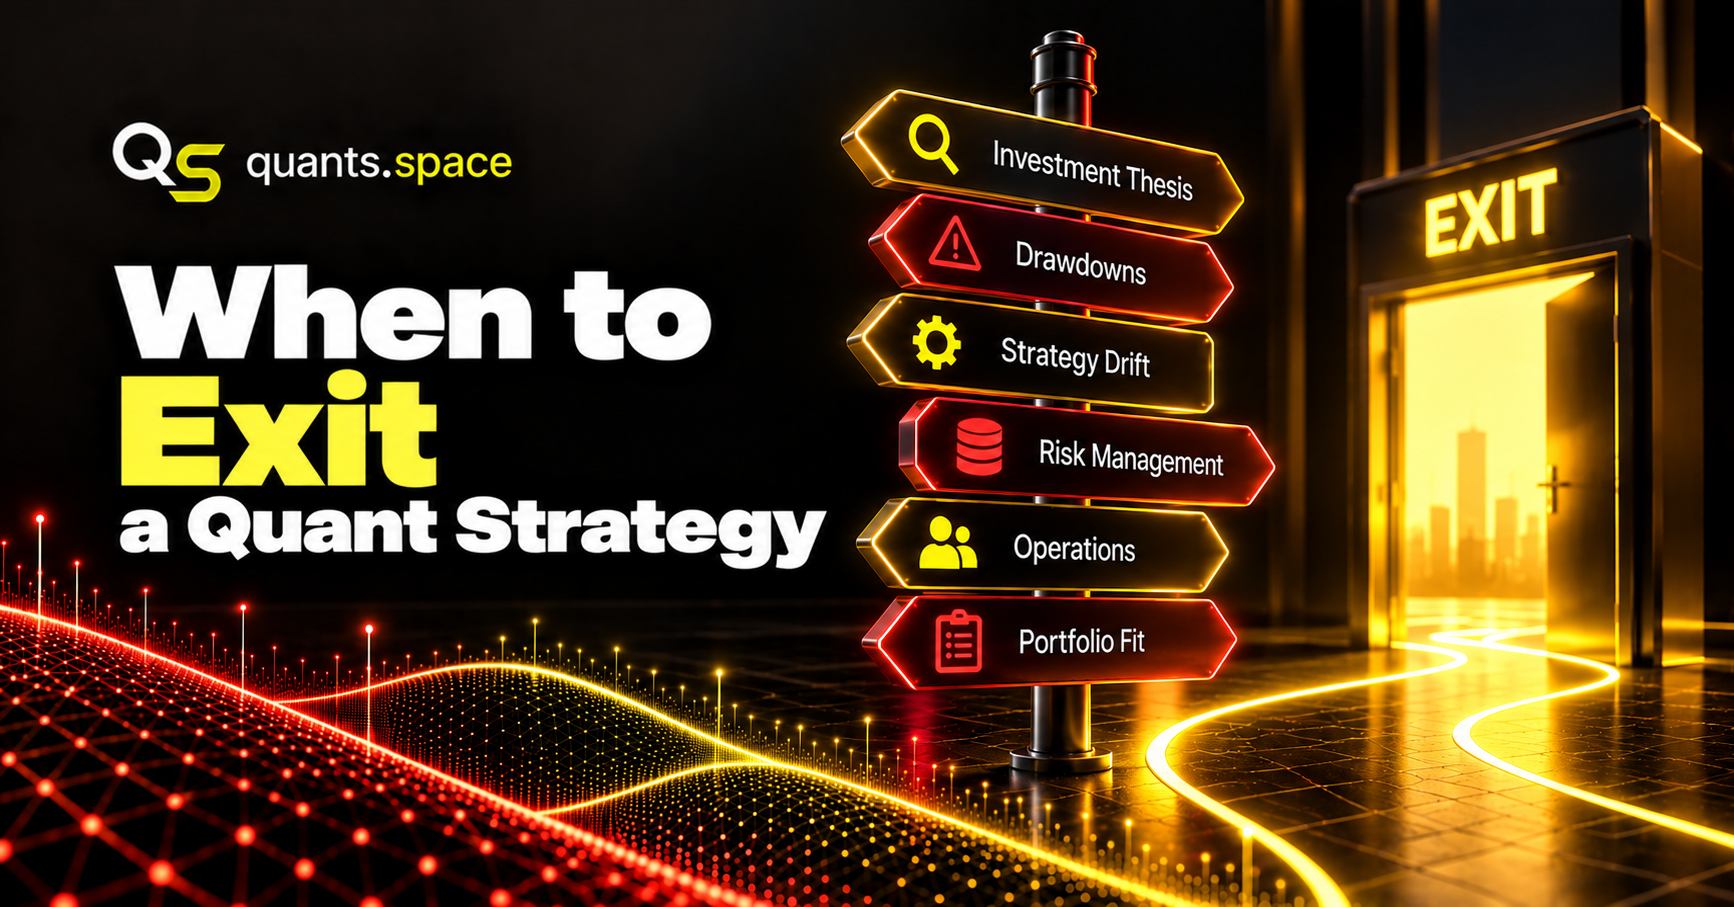
Start With the Original Investment Thesis
Every allocation should have a clear investment rationale. An allocator may select a quant manager for diversification, exposure to specific return drivers, or access to a systematic strategy unavailable within the existing portfolio.
When considering redemption, investors should revisit those initial objectives. Does the strategy still provide the expected exposure? Have its risk characteristics changed, or has the broader portfolio evolved in ways that reduce its usefulness?
A strategy can remain profitable while becoming less relevant to an allocator's objectives. Conversely, temporary losses may be acceptable if the investment thesis remains valid and the strategy continues to operate within expected parameters.
Distinguish Normal Drawdowns From Structural Problems
Drawdowns are inevitable in systematic trading, but their causes and characteristics matter. A trend-following strategy, for example, may struggle in markets with frequent reversals, while a statistical arbitrage strategy may experience losses when historical relationships weaken.
Allocators should compare current losses with historical drawdown patterns, volatility expectations, and stress-test scenarios. The analysis should consider the magnitude and duration of losses, changes in correlations, and whether the strategy's behavior remains consistent with its design.
A drawdown that exceeds historical experience does not automatically mean the strategy has failed. However, unexplained losses, repeated risk limit breaches, or significant deviations from expected behavior may justify a deeper review.
Watch for Strategy Drift
Strategy drift occurs when a manager's investment approach changes materially from the one originally evaluated by investors. These changes may involve new markets, different trading horizons, increased leverage, or modifications to portfolio construction.
Some changes are reasonable responses to evolving market conditions or improvements in research. The concern arises when they alter the strategy's risk profile without sufficient explanation or investor understanding.
Allocators should monitor changes in exposures, factor sensitivities, and sources of return. If the strategy no longer provides the characteristics that justified the original investment, reducing or redeeming the allocation may become appropriate.
Evaluate Risk Management Failures
A manager's risk management framework is particularly important during periods of stress. Institutional investors need confidence that position limits, exposure controls, liquidity management, and operational safeguards continue to function as intended.
Occasional losses within established risk parameters are different from repeated failures to enforce those parameters. Undisclosed leverage increases, unexplained concentration, or breaches that are not addressed promptly can raise serious concerns.
Allocators should examine how the manager identifies problems, communicates them, and implements corrective actions. Persistent weaknesses in risk oversight may warrant redemption even if recent performance has been positive.
Consider Liquidity and Capacity Changes
Liquidity conditions can affect both a strategy's performance and an investor's ability to exit. A manager trading less liquid instruments may face higher transaction costs or greater market impact as assets under management increase.
Allocators should monitor trading volumes, execution costs, portfolio concentration, and estimated strategy capacity. Significant deterioration in these measures can indicate that the strategy is becoming harder to implement efficiently.
Redemption terms also matter. Notice periods, lockups, gates, and other contractual provisions can limit an investor's flexibility, particularly during market stress. Understanding these conditions before a problem emerges is essential for effective portfolio management.
Review Operational and Governance Concerns
Investment performance is only one component of manager oversight. Operational weaknesses, governance problems, or material changes in key personnel can also justify reconsidering an allocation.
Examples include failures in trade reconciliation, cybersecurity incidents, inadequate segregation of duties, or departures of individuals responsible for critical research and trading functions.
Allocators should assess the severity of each issue and the manager's response. A well-managed incident with clear remediation may not require immediate redemption, while repeated failures or a lack of transparency can undermine confidence in the organization.
Assess Portfolio-Level Implications
An allocator may decide to redeem from a quant strategy even when the manager continues to perform as expected. Changes elsewhere in the institutional portfolio can alter the value of an existing allocation.
For example, increasing exposure to similar systematic strategies may create unintended concentration. A manager that previously offered diversification could become highly correlated with other investments as market conditions or portfolio composition change.
Investors should evaluate the strategy's contribution to total portfolio risk, expected returns, liquidity, and diversification. The decision to maintain an allocation should reflect its current role within the portfolio rather than historical performance alone.
Avoid Performance-Chasing Decisions
Recent returns can strongly influence investment decisions, particularly after prolonged losses. However, redeeming solely because a strategy has underperformed may lead investors to exit near the bottom of a drawdown.
Similarly, strong recent performance should not prevent allocators from addressing emerging operational or risk management concerns.
A disciplined review process should combine quantitative evidence with qualitative assessments of the manager's investment process, governance, and communication. Predefined monitoring criteria can help reduce the influence of short-term emotions.
Decide Between Monitoring, Reducing, and Redeeming
Redemption does not have to be an immediate all-or-nothing decision. Depending on the circumstances, allocators may increase monitoring, request additional information, reduce position size, or withdraw capital entirely.
For example, an unexpected drawdown with a credible explanation may justify closer monitoring. A material increase in portfolio overlap could support a partial reduction, while serious governance failures may require a complete exit.
The appropriate response depends on the severity of the concern, the manager's ability to address it, and the consequences for the broader portfolio.
Build a Consistent Redemption Framework
Institutional investors benefit from establishing review criteria before problems arise. These criteria may include performance deviations, risk limit breaches, changes in strategy exposures, operational incidents, and material departures from the original investment thesis.
Clear escalation procedures help determine when concerns require additional due diligence, investment committee review, or a formal redemption decision. The framework should also account for liquidity constraints and the practical timing of capital withdrawals.
Ultimately, the decision to redeem from a quant strategy should reflect whether the investment continues to meet the allocator's objectives. A disciplined process allows investors to respond to meaningful changes while avoiding unnecessary reactions to normal market volatility.